Important Information

This website is managed by Ultima Markets’ international entities, and it’s important to emphasise that they are not subject to regulation by the FCA in the UK. Therefore, you must understand that you will not have the FCA’s protection when investing through this website – for example:

  • You will not be guaranteed Negative Balance Protection
  • You will not be protected by FCA’s leverage restrictions
  • You will not have the right to settle disputes via the Financial Ombudsman Service (FOS)
  • You will not be protected by Financial Services Compensation Scheme (FSCS)
  • Any monies deposited will not be afforded the protection required under the FCA Client Assets Sourcebook. The level of protection for your funds will be determined by the regulations of the relevant local regulator.

Note: UK clients are kindly invited to visit https://www.ultima-markets.co.uk/. Ultima Markets UK expects to begin onboarding UK clients in accordance with FCA regulatory requirements in 2026.

If you would like to proceed and visit this website, you acknowledge and confirm the following:

  • 1.The website is owned by Ultima Markets’ international entities and not by Ultima Markets UK Ltd, which is regulated by the FCA.
  • 2.Ultima Markets Limited, or any of the Ultima Markets international entities, are neither based in the UK nor licensed by the FCA.
  • 3.You are accessing the website at your own initiative and have not been solicited by Ultima Markets Limited in any way.
  • 4.Investing through this website does not grant you the protections provided by the FCA.
  • 5.Should you choose to invest through this website or with any of the international Ultima Markets entities, you will be subject to the rules and regulations of the relevant international regulatory authorities, not the FCA.

Ultima Markets wants to make it clear that we are duly licensed and authorised to offer the services and financial derivative products listed on our website. Individuals accessing this website and registering a trading account do so entirely of their own volition and without prior solicitation.

By confirming your decision to proceed with entering the website, you hereby affirm that this decision was solely initiated by you, and no solicitation has been made by any Ultima Markets entity.

I confirm my intention to proceed and enter this website Please direct me to the website operated by Ultima Markets , regulated by the FCA in the United Kingdom

Important Notice

Ultima Markets does not have an establishment in Singapore and does not operate from Singapore.

Ultima Markets does not provide products or services to citizens or residents of Singapore, and account applications from Singapore citizens or residents will not be accepted.

If you are a citizen or resident of Singapore, please do not open an account or use Ultima Markets’ products or services.

By selecting “Acknowledge and Continue Browsing”, you confirm that you are accessing this website on your own initiative and that your access is not the result of any direct marketing, targeted advertising, solicitation, or promotional activity by Ultima Markets.

Nothing on this website constitutes an offer, solicitation, or promotion of products or services in any jurisdiction where such activity is prohibited. You are responsible for ensuring that your access to and use of this website complies with applicable local laws and regulations.

Acknowledge and Enter the Website
Roll Arrow

美債殖利率是什麼意思?讀懂標售定價、殖利率曲線與倒掛

Ultima Markets Silver & Gold Trading Icon
Buy: 0.00
Sell: 0.00%

摘要:

  • 美債殖利率與債券價格反向變動,10 年期品種由財政部每月標售定價,是全球借貸定價的主要參考。本文講清標售機制、殖利率曲線與倒掛的歷史表現,以及殖利率對美元、黃金等資產的傳導,並在結尾列出判讀清單。

美債殖利率指的是持有美國公債到期的年化回報率,與債券價格反向變動,10 年期品種是全球借貸定價的主要參考。

圍繞它有幾處容易讀錯:殖利率由每月標售定價、曲線倒掛常被當作衰退訊號、價格與殖利率反向。本文講清標售機制、倒掛的歷史表現與對匯率的傳導,並列出判讀要點。

一、美債殖利率是什麼

1. 價格與殖利率反向

美國公債按固定票息付息,到期償還面值。殖利率把買入價格、票息與期限折算成年化回報:價格下跌,殖利率上升;價格上漲,殖利率下降。新聞裡寫“美債價格下跌”與“美債殖利率上行”,描述的是同一件事。

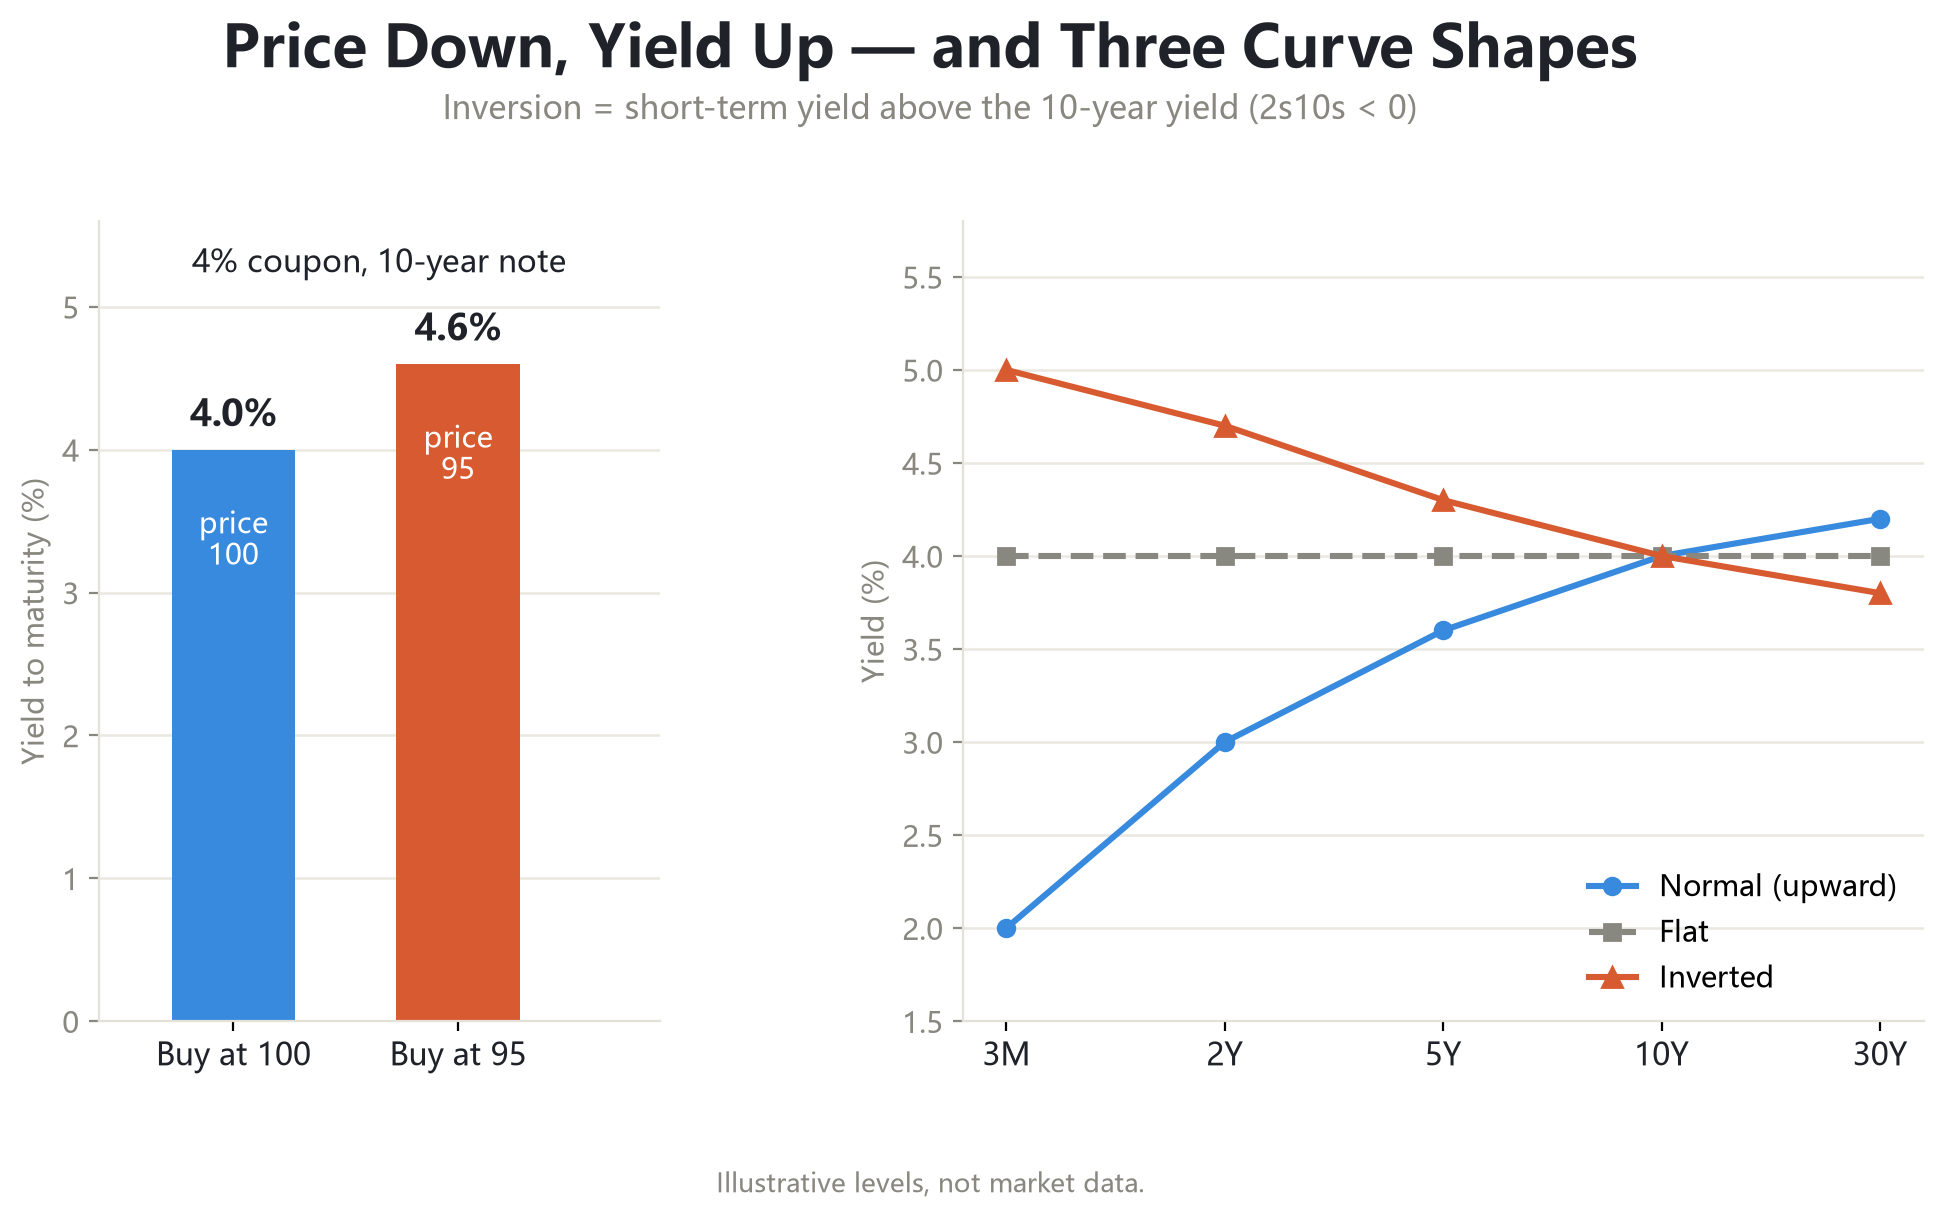
舉例:票息 4% 的 10 年期公債,按面值 100 買入,到期殖利率約為 4%;價格跌到 95 買入,到期殖利率升到約 4.6%。同樣的票息,買入價越低,年化回報越高。

到期殖利率假設持有到期、票息按同一利率再投資,是一個折算口徑。中途賣出的實際回報還取決於賣出時的價格,持有期間價格波動會造成賬面盈虧。

2. 10 年期公債怎麼定價:標售機制

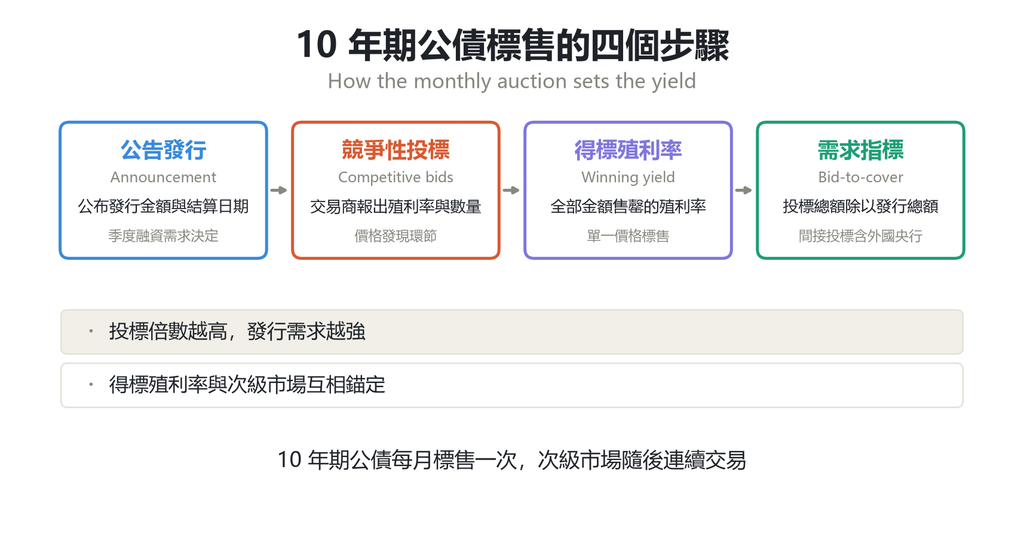
美國財政部每月發行 10 年期公債,流程固定:

• 公告:發行前財政部公布本次發行金額與結算日期。

• 競價:交易商提交競爭性投標,寫明願意接受的殖利率與購買數量。

• 出清:讓全部發行金額售罄的殖利率就是中標殖利率,中標者按同一殖利率成交,屬於單一價格標售。

• 計量:投標總額除以發行總額得到投標倍數,倍數越高需求越強;來自基金與外國央行的間接投標人占比單獨公布。

二級市場隨後連續交易,殖利率隨買賣實時變動,標售的中標殖利率與二級市場互相錨定。發行金額按財政部的季度融資需求調整,近年 10 年期單次發行規模在數百億美元量級。(推薦閱讀:2026美國10年期公債殖利率攻略:全面解析如何影響股市、經濟與個人投資)

10 年期公債標售的四個步驟
10 年期公債標售的四個步驟

3. 為什麼 10 年期是全球基準

美國公債市場規模超過 28 兆美元,是全球交易量最大的債券市場。10 年期品種處於曲線中段,同時反映政策預期與長期增長、通膨預期,美國房貸利率與企業債定價都以它為參考,美元資產在全球組合裡的配置成本也盯住這個數字。

公債價格與殖利率反向關係,以及正常、平坦與倒掛三種殖利率曲線形態示意
公債價格與到期殖利率反向關係,以及正常、平坦、倒掛三種殖利率曲線形態(示意數字)

它與聯邦資金利率的分工要分清:短端利率由聯準會決定,長端殖利率由市場交易決定。兩者方向多數時候一致,緊縮循環的頂部與底部附近可以脫節,脫節本身就是預期變化的線索。

二、殖利率曲線與倒掛

1. 曲線的正常形態與倒掛的定義

把不同期限的公債殖利率連成線,就是殖利率曲線。正常形態向上傾斜:期限越長,投資者要求的補償越高。倒掛指短端殖利率高於長端,最常用 2 年期減 10 年期的利差(2s10s)衡量。

兩個期限反映的內容不同:2 年期主要跟隨聯準會的政策路徑,10 年期還包含未來十年的增長與通膨預期,外加期限溢價。期限溢價是投資者為鎖定長期資金要求的額外補償,公債發行規模與需求的變化會改變它。倒掛意味著市場預計政策利率將來會下行。

2. 2022–2024 那次倒掛

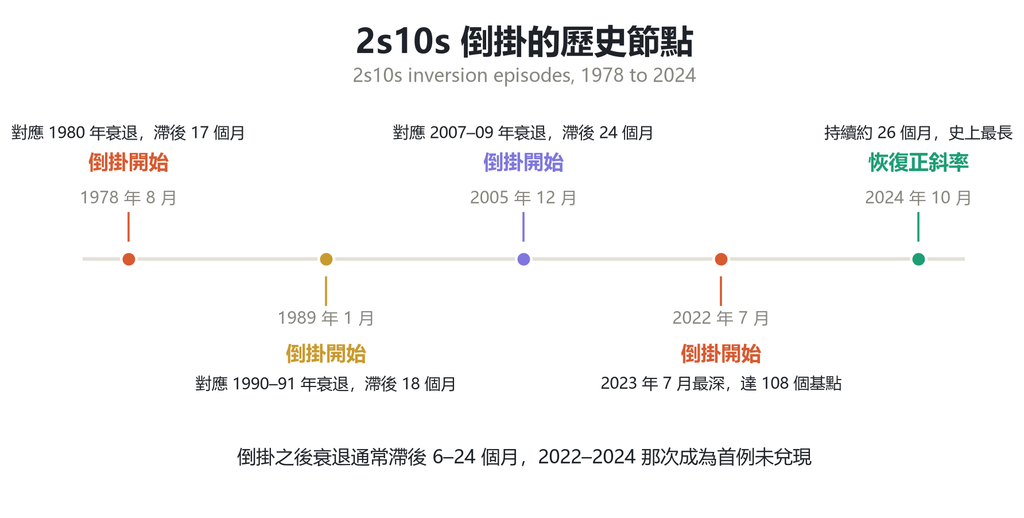
聯準會在 2022 年把聯邦資金利率從近零升到 5.25% 以上。2 年期殖利率升到 5% 附近,10 年期約 4%,2s10s 從 2022 年 7 月起倒掛。倒掛最深的讀數出現在 2023 年 7 月,達 108 個基點,是 1980 年代初以來最深的一次。曲線直到 2024 年 10 月才恢復正斜率,倒掛持續約 26 個月,是有紀錄以來最長的一次。

那輪緊縮的背景是疫情後的通膨上行:聯準會從 2022 年 3 月開始升息,一年多時間把政策利率推高逾 5 個百分點,短端跟隨政策快速上行,長端包含了對未來降息的預期,漲幅落後,倒掛由此形成並加深。(推進閱讀:聯準會利率決議是什麼?一文看懂FOMC議息會議、升息降息與點陣圖怎麼看)

3. 倒掛為什麼受關注

銀行靠借短放長賺取利差,曲線倒掛壓縮放貸收益,信貸收縮會拖慢經濟。歷史上倒掛之後出現衰退的滯後通常在 6 到 24 個月之間:1978 年 8 月倒掛對應 1980 年衰退,1989 年 1 月對應 1990–91 年衰退,2005 年 12 月對應 2007–09 年衰退。

兩處例外要記下:一是在聯準會的研究裡,3 個月對 10 年期利差的預測記錄比 2s10s 更好;二是 2022–2024 那次倒掛持續 26 個月,衰退判定沒有出現,成為現代紀錄裡的首例未兌現。衰退通常在曲線恢復正斜率之後纔開始,倒掛本身沒有給出觸發時點。滯後區間長也意味著倒掛出現後的幾個月,消費與企業盈利數據仍可能強勁,訊號的確認要等更後面的數據。

2s10s 倒掛的歷史節點,1978 至 2024 年
2s10s 倒掛的歷史節點,1978–2024

三、對匯率的傳導

1. 利差驅動美元

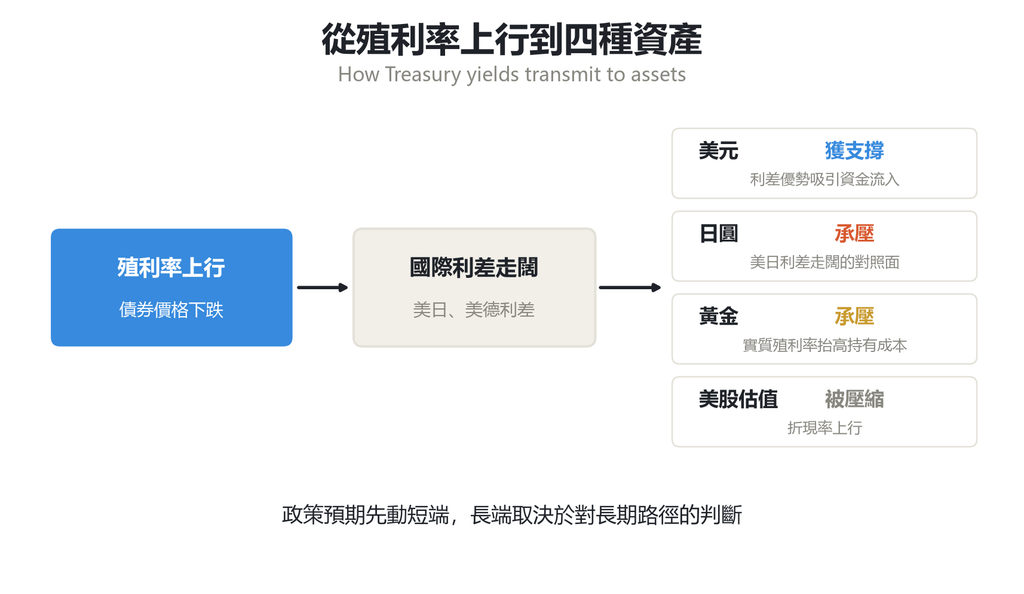
美元的方向與美國和其他經濟體的利差相關。美日、美德 10 年期利差常被用來解釋日圓與歐元的走勢:利差走闊,資金傾向流向美元資產,美元獲得支撐;利差收窄,支撐隨之減弱。2022 年到 2024 年那輪利差走闊期間,美元兌日圓升到 160 附近,日本當局多次入場干預,是利差傳導最直接的一段歷史記錄。

2. 政策預期先動短端

聯準會的升息或降息預期先改變 2 年期殖利率,10 年期的變化幅度取決於市場對長期路徑的判斷。同一輪緊縮裡,短端可以升得比長端快,曲線因此走平甚至倒掛;寬鬆預期出現時,短端下行更快,曲線重新變陡。

3. 觀察清單

• 2s10s 利差:倒掛與恢復正斜率的歷史節點,看曲線形態變化。

• 10 年期實質殖利率:以通膨保值債券(TIPS)衡量,剔除通膨預期後的實際回報。

• 投標倍數與間接投標占比:標售需求強弱與海外買盤。

• 與日德公債的利差:直接對應美元兌日圓、美元兌歐元的定價。

殖利率向美元、日圓、黃金與美股估值的傳導

四、判讀要點與常見誤區

1. 價格與殖利率方向別混淆

債券報價常用價格,行情軟體與新聞常引用殖利率。作多債券等於放空殖利率,兩者盈虧相反。行情軟體裡 US10Y 這類代碼的報價是殖利率,數值上漲對應債券價格下跌,寫交易計畫前先確認看的是哪一個口徑。

2. 倒掛不是擇時工具

滯後 6 到 24 個月、幅度不定,2022–2024 那次沒有出現衰退。把倒掛當成賣出風險資產的觸發條件,歷史上會反覆失效。

3. 名目殖利率與實質殖利率分開看

名目殖利率減去通膨預期等於實質殖利率。黃金與美元的定價對實質殖利率更敏感,通膨預期上行時,名目殖利率上行未必壓低金價。實質殖利率可以由 10 年期通膨保值債券直接讀出,也可以用名目殖利率減去通膨預期估算,兩種算法的結果差別不大。

總結

10 年期美債殖利率由標售定價與二級市場交易共同決定,曲線形態反映政策與增長的預期差,倒掛的歷史記錄值得參考,但不是擇時訊號。想練習跟蹤這套定價,可以用Ultima Markets的MT5模擬帳戶,觀察美元兌日圓、美元兌歐元在數據與標售結果發布時點的反應,配合正文列出的觀察清單逐項核對。當您準備好進行實際操作時,可考慮隨即開立真實帳戶,審慎進行投資佈局。您也能透過Ultima Markets訂閱電子書,或是參加Ultima教育學院講座,免費學習更多投資技巧。

FAQ

Q1:美債殖利率上升是利多還是利空美元?

通常支撐美元:利差優勢擴大,吸引資金流入美元資產。但要區分上行來自增長預期還是通膨預期,兩者的後續路徑不同。

Q2:殖利率曲線倒掛一定預示衰退嗎?

歷史上倒掛後 6 到 24 個月內出現過多數衰退,但 2022–2024 那次持續 26 個月沒有出現衰退判定,倒掛不是可靠的觸發條件。

Q3:10 年期美債殖利率在哪裡看?

財政部標售結果與二級市場報價都公開,MT5 等行情軟體可以查看 US10Y 相關報價,實時更新。

風險提示

本文為教育用途,不構成投資建議。差價合約與保證金交易存在高風險,可能導致損失全部本金,請根據自身風險承受能力謹慎決策。

立即分享

  • Article Details
  • Article Details
  • Article Details

免責聲明: 本內容僅供信息參考之用,不構成,也不應被視為任何形式的金融、投資或其他專業建議。文中所述觀點或意見,均不代表 Ultima Markets 或作者對任何具體投資產品、策略或交易行為的推薦。讀者在做出投資決策時,不應僅依賴本內容,建議根據自身情況尋求獨立的專業意見。

目錄

  • 一、美債殖利率是什麼
  • 二、殖利率曲線與倒掛
  • 三、對匯率的傳導
  • 四、判讀要點與常見誤區
  • 總結
  • FAQ
  • 風險提示

Thank you for visiting the Ultima Markets website. Please note that this website is intended for individuals residing in jurisdictions where accessing is permitted by law. Ultima and its affiliated entities do not operate in your home jurisdictions.

By clicking on ''Acknowledge'', you confirm that you are entering this website solely based on your initiative and not as a result of any specific marketing outreach. You wish to obtain information from this website based on reverse solicitation principles, in accordance with the applicable laws of your home jurisdiction.