This website is managed by Ultima Markets’ international entities, and it’s important to emphasise that they are not subject to regulation by the FCA in the UK. Therefore, you must understand that you will not have the FCA’s protection when investing through this website – for example:
You will not be guaranteed Negative Balance Protection
You will not be protected by FCA’s leverage restrictions
You will not have the right to settle disputes via the Financial Ombudsman Service (FOS)
You will not be protected by Financial Services Compensation Scheme (FSCS)
Any monies deposited will not be afforded the protection required under the FCA Client Assets Sourcebook. The level of protection for your funds will be determined by the regulations of the relevant local regulator.
Note: UK clients are kindly invited to visit https://www.ultima-markets.co.uk/. Ultima Markets UK expects to begin onboarding UK clients in accordance with FCA regulatory requirements in 2026.
If you would like to proceed and visit this website, you acknowledge and confirm the following:
1.The website is owned by Ultima Markets’ international entities and not by Ultima Markets UK Ltd, which is regulated by the FCA.
2.Ultima Markets Limited, or any of the Ultima Markets international entities, are neither based in the UK nor licensed by the FCA.
3.You are accessing the website at your own initiative and have not been solicited by Ultima Markets Limited in any way.
4.Investing through this website does not grant you the protections provided by the FCA.
5.Should you choose to invest through this website or with any of the international Ultima Markets entities, you will be subject to the rules and regulations of the relevant international regulatory authorities, not the FCA.
Ultima Markets wants to make it clear that we are duly licensed and authorised to offer the services and financial derivative products listed on our website. Individuals accessing this website and registering a trading account do so entirely of their own volition and without prior solicitation.
By confirming your decision to proceed with entering the website, you hereby affirm that this decision was solely initiated by you, and no solicitation has been made by any Ultima Markets entity.
Ultima Markets does not have an establishment in Singapore and does not operate from Singapore.
Ultima Markets does not provide products or services to citizens or residents of Singapore, and account applications from Singapore citizens or residents will not be accepted.
If you are a citizen or resident of Singapore, please do not open an account or use Ultima Markets’ products or services.
By selecting “Acknowledge and Continue Browsing”, you confirm that you are accessing this website on your own initiative and that your access is not the result of any direct marketing, targeted advertising, solicitation, or promotional activity by Ultima Markets.
Nothing on this website constitutes an offer, solicitation, or promotion of products or services in any jurisdiction where such activity is prohibited. You are responsible for ensuring that your access to and use of this website complies with applicable local laws and regulations.
Ultima Markets Daily Market Insights – December 19, 2025
Today marks the culmination of a pivotal week for central banks. With US inflation data confirming the Fed’s dovish path and the Bank of England delivering a contested rate cut, attention now turns to Tokyo for a potentially historic move by the Bank of Japan.
US CPI: The “Dove’s Gift” & Fed Outlook 2026
Yesterday’s delayed November US CPI report provided the clarity the Federal Reserve—and the market—needed to reinforce expectations for a continued easing cycle into 2026:
Headline CPI cooled significantly to 2.7% YoY (from 3.0% in September)
Core CPI slipped to 2.6% YoY (from 3.1%).
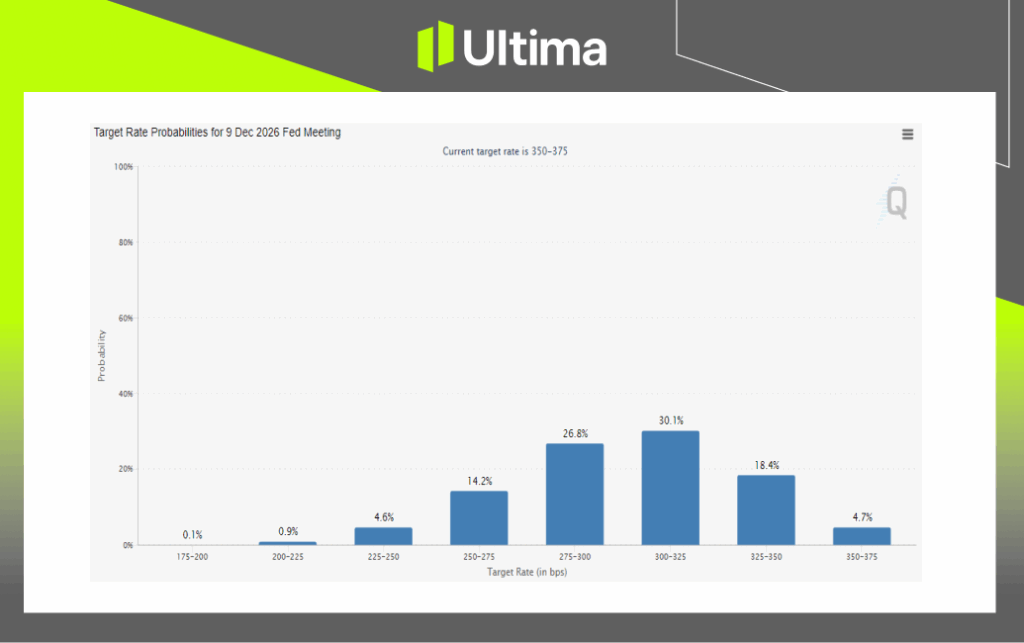
The undershoot surprised markets, removing the inflation barrier for the Fed and effectively “greenlighting” further rate cuts. Markets now anticipate the Fed may continue its easing cycle in Q1 2026, with the Fed Funds Rate projected to fall to a terminal range of 3.00%–3.25%.
Fed Target Rate Probabilities in December 2026 | Source: CME FedWatch
The confirmation of disinflation reinforces the bearish trend for the US Dollar. With real yields expected to compress further, the USD is vulnerable to a breakdown below 98.00, signaling the end of the “higher-for-longer” narrative.
USDX, H4 Chart | Ultima Markets MT5
The Dollar has seen a near-term rebound around 98.00, suggesting the move was largely priced in. Any rebound below the key resistance zone of 98.80–99.00 will likely remain a “sell the rally” opportunity.
The broad outlook for the USD remains bearish, particularly if upcoming BoJ decisions trigger further volatility in the FX market.
Bank of England (BoE): A “Hawkish Cut”?
The Bank of England delivered a nuanced message yesterday, cutting rates while signaling that future easing will be conditional—earning the market label of a “Hawkish Cut.”
The Decision: The BoE cut the Bank Rate by 25 bps to 3.75%. However, the vote was deeply divided (5-4 split), with four members voting to hold rates, citing persistent service inflation risks.
The “Cautious” Stance: Despite the cut, the BoE’s tone was restrictive. The MPC warned that future cuts are “not guaranteed” and will become a “closer call” moving forward, effectively pushing back against aggressive easing bets.
While the rhetoric was restrictive, market positioning still reflects expectations for a more accommodative path, with traders pricing in 2–3 cuts for 2026, targeting a Bank Rate near 3.25% by mid-year.
GBPUSD, H4 Chart | Ultima Markets MT5
GBPUSD rejected resistance near 1.344 three times, signaling limited near-term upside.
Despite the cautious BoE tone, recent sluggish UK data suggest that further accelerated cuts may still be expected in 2026, the immediate upside for Sterling remains capped.
What to Expect from BoJ Today?
The Bank of Japan delivered its widely anticipated rate hike today, the Board voted unanimously to raise the uncollateralized overnight call rate to 0.75% (from 0.50%). This marks the highest policy rate in Japan since September 1995.
The central bank cited a “moderate recovery” in the Japanese economy and the need to address persistent cost-push inflation as primary drivers for the move. The decision confirms that the BoJ is shifting focus from fighting deflation to managing inflation sustainability.
Despite the hike, the initial market reaction has been counter-intuitive—a classic “sell the fact” move. The USD/JPY actually edged higher (Yen weakened) toward 156.00 immediately following the announcement.
Why? The hike was fully priced in by markets. Investors are interpreting the move as a “dovish hike,” anticipating that future rate increases will be extremely gradual into 2026–2027. The focus now shifts entirely to Governor Kazuo Ueda’s press conference.
Traders are waiting to see if he signals a pause or hints at another hike in early 2026. Unless Ueda sounds surprisingly hawkish, the Yen may struggle to sustain gains today.
Disclaimer
Comments, news, research, analysis, price, and all information contained in the article only serve as general information for readers and do not suggest any advice. Ultima Markets has taken reasonable measures to provide up-to-date information, but cannot guarantee accuracy, and may modify without notice. Ultima Markets will not be responsible for any loss incurred due to the application of the information provided.
Thank you for visiting the Ultima Markets website. Please note that this website is intended for individuals residing in jurisdictions where access is permitted by law. Ultima and its affiliated entities do not operate in your home jurisdiction.
By clicking ‘Acknowledge’, you confirm that you are entering this website solely on your own initiative and not as a result of any specific marketing outreach. You wish to obtain information from this website based on reverse solicitation principles, in accordance with the applicable laws of your home jurisdiction.