This website is managed by Ultima Markets’ international entities, and it’s important to emphasise that they are not subject to regulation by the FCA in the UK. Therefore, you must understand that you will not have the FCA’s protection when investing through this website – for example:
You will not be guaranteed Negative Balance Protection
You will not be protected by FCA’s leverage restrictions
You will not have the right to settle disputes via the Financial Ombudsman Service (FOS)
You will not be protected by Financial Services Compensation Scheme (FSCS)
Any monies deposited will not be afforded the protection required under the FCA Client Assets Sourcebook. The level of protection for your funds will be determined by the regulations of the relevant local regulator.
Note: UK clients are kindly invited to visit https://www.ultima-markets.co.uk/. Ultima Markets UK expects to begin onboarding UK clients in accordance with FCA regulatory requirements in 2026.
If you would like to proceed and visit this website, you acknowledge and confirm the following:
1.The website is owned by Ultima Markets’ international entities and not by Ultima Markets UK Ltd, which is regulated by the FCA.
2.Ultima Markets Limited, or any of the Ultima Markets international entities, are neither based in the UK nor licensed by the FCA.
3.You are accessing the website at your own initiative and have not been solicited by Ultima Markets Limited in any way.
4.Investing through this website does not grant you the protections provided by the FCA.
5.Should you choose to invest through this website or with any of the international Ultima Markets entities, you will be subject to the rules and regulations of the relevant international regulatory authorities, not the FCA.
Ultima Markets wants to make it clear that we are duly licensed and authorised to offer the services and financial derivative products listed on our website. Individuals accessing this website and registering a trading account do so entirely of their own volition and without prior solicitation.
By confirming your decision to proceed with entering the website, you hereby affirm that this decision was solely initiated by you, and no solicitation has been made by any Ultima Markets entity.
Ultima Markets does not have an establishment in Singapore and does not operate from Singapore.
Ultima Markets does not provide products or services to citizens or residents of Singapore, and account applications from Singapore citizens or residents will not be accepted.
If you are a citizen or resident of Singapore, please do not open an account or use Ultima Markets’ products or services.
By selecting “Acknowledge and Continue Browsing”, you confirm that you are accessing this website on your own initiative and that your access is not the result of any direct marketing, targeted advertising, solicitation, or promotional activity by Ultima Markets.
Nothing on this website constitutes an offer, solicitation, or promotion of products or services in any jurisdiction where such activity is prohibited. You are responsible for ensuring that your access to and use of this website complies with applicable local laws and regulations.
The November Macro Shift and the Return of the Hawkish Fed
The November Macro Shift and the Return of the Hawkish Fed
The macroeconomic landscape of November 2026 has been abruptly redefined by the potent combination of resilient labor data and stubbornly hot inflation. Following the recent Non-Farm Payrolls (NFP) and Consumer Price Index (CPI) releases, financial markets have aggressively repriced their expectations for the Federal Reserve’s upcoming December meeting.
The narrative has definitively shifted away from any lingering hopes of a rate pause. Instead, the market is now fully pricing in a December rate hike, fundamentally altering the trajectory for the US Dollar, Gold, and US Equities as we head into the end of the year.
NFP, CPI, and the December Fed Repricing
The dual shock of the latest NFP and CPI reports has served as a brutal reality check for the markets. The NFP data demonstrated that the US labor market remains surprisingly robust, showing no signs of the cooling required to bring wage inflation down to the Fed’s target. Days later, the CPI print confirmed the market’s worst fears: inflation is not just sticky, but potentially re-accelerating in key core sectors.
US NFP & CPI Print for October:
US CPI: +0.4% MoM vs Prior 0.6% (Consensus: 0.3%); US Core CPI: +0.3% MoM vs Prior 0.3% (Consensus: 0.2%)
US Non-Farm Payrolls: +165K vs Prior 60K (Consensus: 65K)
This data sequence has completely reshaped the interest rate futures market—or more precisely, it has solidified hike expectations in a previously uncertain market. Prior to these releases, a December hike was seen as a mere possibility; it is now viewed as a near certainty. The data has validated the Federal Reserve’s restrictive posture, leaving policymakers with little choice but to maintain—and potentially escalate—their fight against inflation.
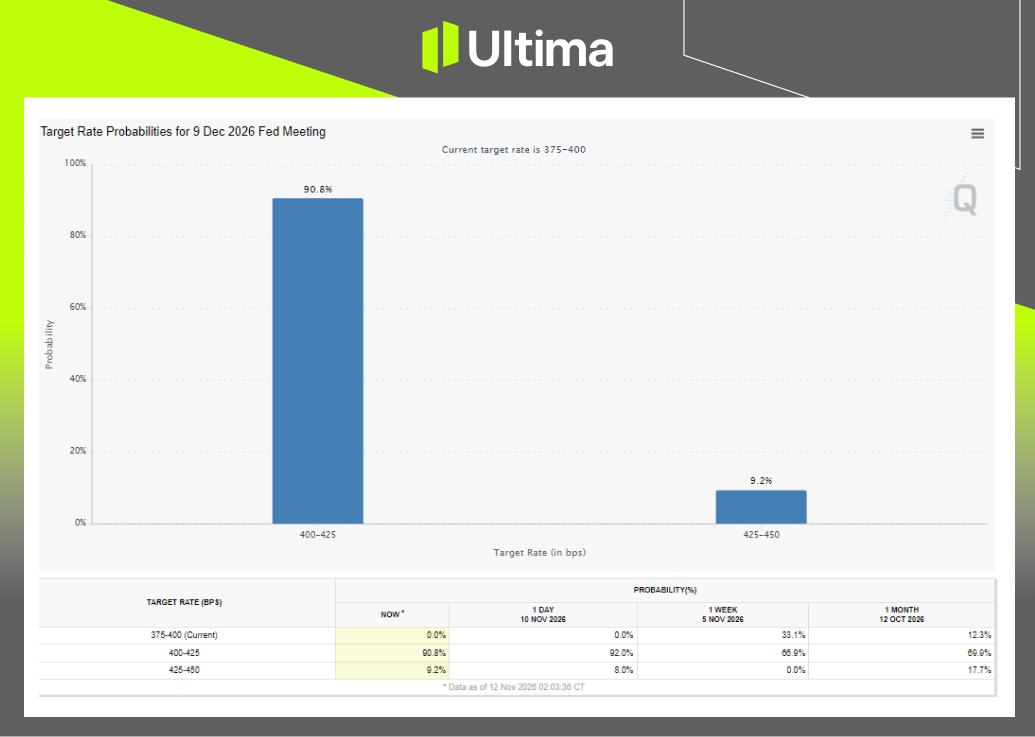
Fed December Hike Probability | Source: CME Group
According to the CME FedWatch data, the futures market has now priced in a 90.8% probability of a 25-basis-point hike, while 9.2% anticipate a jumbo 50-basis-point hike.
The Escalation: Is a 50-Basis-Point Hike on the Table?
The immediate implication of this data is a guaranteed 25-basis-point hike in December, but the hawkish repricing does not stop there. Recent commentary from Federal Reserve officials has taken a notably aggressive turn. Policymakers have openly stated that if inflation remains stubborn and the labor market continues its resilient streak, the committee may even consider a 50-basis-point hike.
Christopher Waller (Fed Governor): In a speech in London, Waller stated he would initially lean toward a 25-basis-point hike, but warned that if the October core CPI came in at 0.3% or higher, a larger 50-basis-point move “should be considered” to protect the central bank’s inflation-fighting credibility.
Lorie Logan (Dallas Fed President): Expressed support for a faster pace of tightening, noting that rates need to rise by at least 50 basis points more to make policy sufficiently restrictive.
This escalation in rhetoric is a severe headwind for risk assets. The mere threat of a 50-bps move signals that the Fed’s terminal rate may need to be revised higher, fundamentally increasing the cost of capital and tightening global liquidity conditions far beyond what was priced in just a month ago.
Asset Class Implications: Navigating the Yield Shock
The sudden hawkish shift has triggered a sharp surge in US Treasury yields, sending shockwaves across major asset classes. Here is the outlook for the US Dollar, Gold, and US Equities.
The US Dollar: Bullish Momentum vs. Over-Pricing Risks
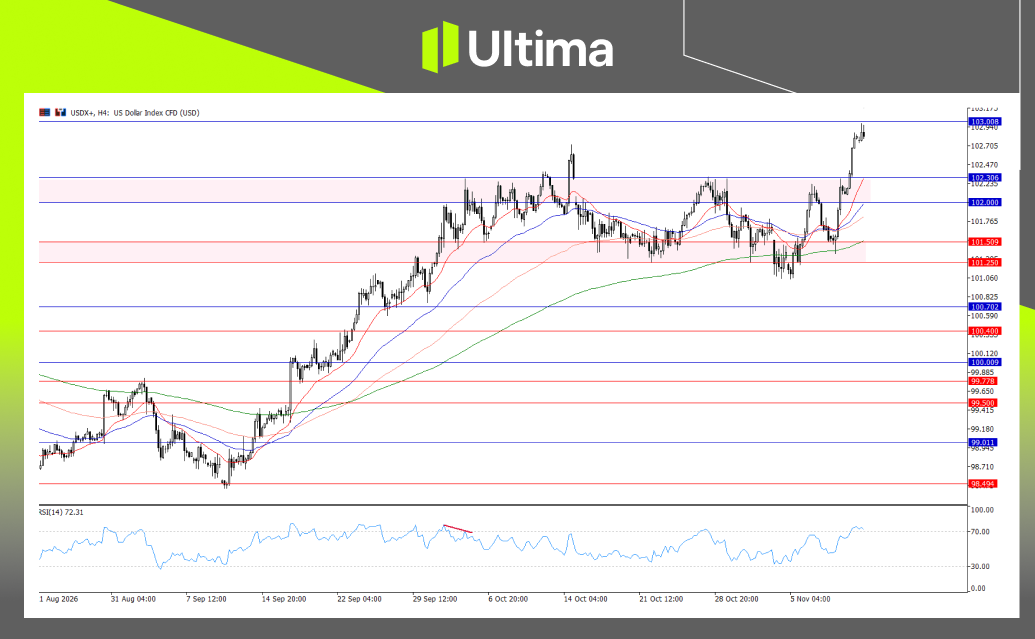
The US Dollar has been the primary beneficiary of the NFP and CPI data. Driven by the surge in rate hike bets, the Dollar Index (DXY) recently shattered its 20-month high, breaking through the 102.90 level.
USDX, H4 Chart | Source: Ultima Markets MT5
The Technical Outlook: The momentum is aggressively bullish, but the Dollar Index is now testing a crucial structural resistance zone at 103.00. A decisive weekly close above 103.00 would open the door for a much broader multi-month rally.
What to Watch: While the hawkish hype provides a powerful catalyst for further dollar strength, traders must exercise caution. The market has priced in the December hike very rapidly. When expectations become this universally hawkish, the market becomes vulnerable to a “buy the rumor, sell the fact” scenario. If the dollar becomes overly priced for perfection, any slight data miss could trigger sharp profit-taking. However, until clear bearish price action materializes at the 103.00 resistance, the fundamental trend for the dollar remains strictly bullish.
Gold (XAU/USD): The Yield-Driven Squeeze
Gold is facing severe structural headwinds in this environment. The precious metal is highly sensitive to real interest rates, and the recent sharp surge in US Treasury yields has dramatically increased the opportunity cost of holding non-yielding assets.
With the Fed actively discussing 25 to 50-basis-point hikes and the US Dollar dominating the currency space, Gold is being squeezed out of portfolios. Expect the precious metal to face continued downside pressure as long as the December rate hike narrative dictates the pace of the bond market.
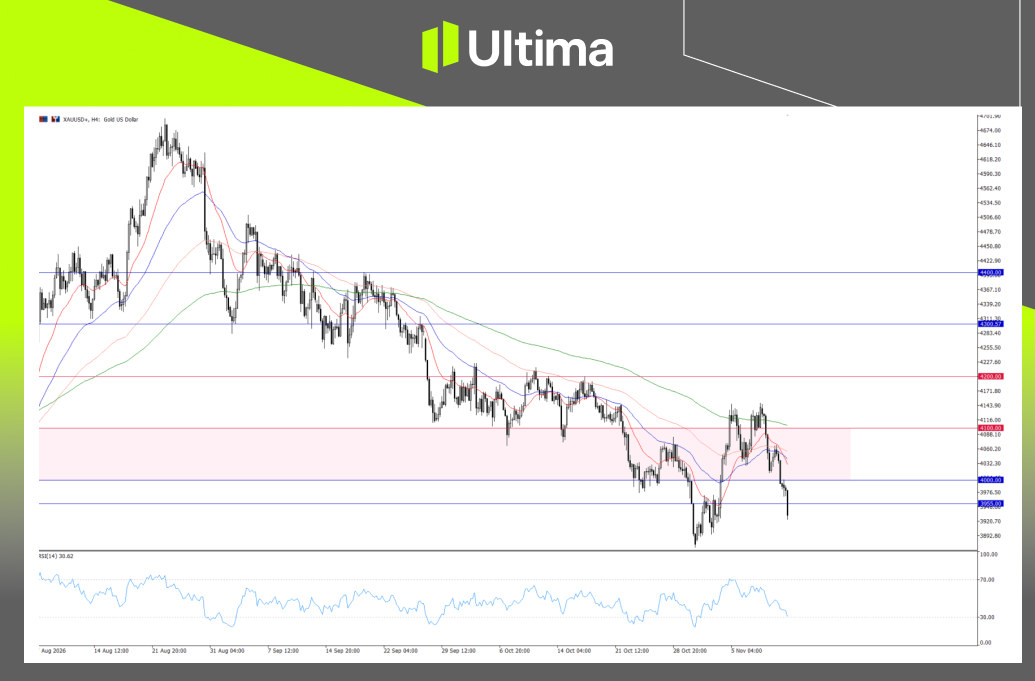
XAUUSD, H4 Chart | Source: Ultima Markets MT5
The Technical Outlook: Gold has now broken below the $4,000 level after a failed attempt to regain the $4,000–$4,100 major structural zone. This second break below $4,000 within a single month suggests sustained downward pressure and a loss of bullish control in the gold market.
US Equities: The AI Capex Fear and the Rate Reality
The outlook for US Equities demands extreme caution. Following the brutal October tech sell-off—triggered by fears over unsustainable AI capital expenditures (capex) and cash burn—the market managed to stage a sharp, relief-driven recovery.
However, this recovery is now on fragile ground. The combination of surging Treasury yields and a hawkish Federal Reserve adds a massive fundamental headwind to equity valuations. Growth and tech stocks, which dominate the major indices, are particularly vulnerable to a higher-for-longer cost of capital.
If the AI capex fears that sparked the October panic reignite, they will now be compounded by the reality of a tightening Fed. This double-threat scenario—slowing tech profitability metrics colliding with rising interest rates—creates a highly treacherous environment for equities, capping upside potential and leaving the market exposed to a deeper structural correction.
The convergence of sticky inflation and a resilient labor market has backed the Federal Reserve into a hawkish corner, ensuring that a December rate hike is effectively locked in.
As policymakers float the possibility of a 50-basis-point move, global liquidity conditions are rapidly tightening. Moving into the final weeks of the year, traders must respect the macroeconomic shift: surging Treasury yields will continue to provide a massive fundamental tailwind for the US Dollar, while relentlessly squeezing non-yielding assets like Gold and fundamentally challenging the valuations of high-beta US tech equities.
Disclaimer
Comments, news, research, analysis, price, and all information contained in the article only serve as general information for readers and do not suggest any advice. Ultima Markets has taken reasonable measures to provide up-to-date information, but cannot guarantee accuracy, and may modify without notice. Ultima Markets will not be responsible for any loss incurred due to the application of the information provided.
Thank you for visiting the Ultima Markets website. Please note that this website is intended for individuals residing in jurisdictions where access is permitted by law. Ultima and its affiliated entities do not operate in your home jurisdiction.
By clicking ‘Acknowledge’, you confirm that you are entering this website solely on your own initiative and not as a result of any specific marketing outreach. You wish to obtain information from this website based on reverse solicitation principles, in accordance with the applicable laws of your home jurisdiction.